

Monthly Foreign Exchange Review
October currency market performance varied considerably by currency and country. Individual currencies had independent responses to events, with the EUR consolidating while MXN continued its fall vs the USD. Oil and Energy prices had less impact on currencies compared to prior months in 2026.
USD mixed, US Economy mixed, inflation high on energy costs
The US economy gave mixed signals in October, with weak employment numbers, solid GDP growth and higher inflation numbers.
The US GDP numbers showed solid growth in Q3 at 3.4% beating estimates. Retail sales rose 0.8% and excluding autos rose 0.9%. Consumer confidence ticked up from low levels to 91. ISM Manufacturing index remained solid at 55.5. The US economic growth numbers tell us the US economy is growing at a sustained and good pace.
US unemployment underperformed in October, adding only 29,000 jobs. Unemployment rose to 4.2% while average inflation adjusted earnings fell -0.1%. Employment has been variable over 2026 with months of high growth followed by weaker months. 2026 average job growth is 68k jobs per month, and it is clear job growth is sluggish. The question: Why is strong GDP growth not causing strong jobs growth? Possible answers are high productivity growth (4.9% in Q3) and AI adoption causing more output with the same employment, and talks with decision makers are telling us companies are happy with current situation but wary of future company prospects.
US inflation came in very strong in October with some numbers posting the highest rates since 2022. PPI final demand came in at 1.3% month over month. CPI month over month was 0.6%. These high inflation numbers are causing real economic pain as real hourly earnings fell -0.7% year over year, and this number has only been lower during the great recession and during COVID. Energy costs are driving the reported inflation numbers, but the feel is “prices are higher on everything”. Inflation is a real and ongoing problem for the US economy.
US interest rates fell in October, pulling back from the multi-decade highs posted early in the month. 10-year rates hit 5.36% on 10/7, and this was the highest since June of 2002. Mortgage rates hit 7.53% on 10/10 before falling to 7.38% at the end of the month. The next FOMC meeting is December 9th, and expectations are currently 75% for a rate hike to 4.25%
The USD was mixed vs individual currencies, while the USD index was largely flat. The US Dollar index gained 0.23% but this disguised moves of +1.1% vs the EUR, losing -0.82% vs the CNY, and gaining +2.5% vs the MXN. Tariffs, rate hikes and global uncertainty are all structural tailwinds for the USD, and we do expect these to continue through the end of 2026.
Oil prices remain a “known unknown” for the world economy and currency markets. The end of October saw large daily ranges for oil prices and US oil traded above $100 a barrel with a spike to above $110. Currency markets could move dramatically if there are changes to the situation with Iran and oil prices.
EURUSD
Source: Bloomberg Finance LP
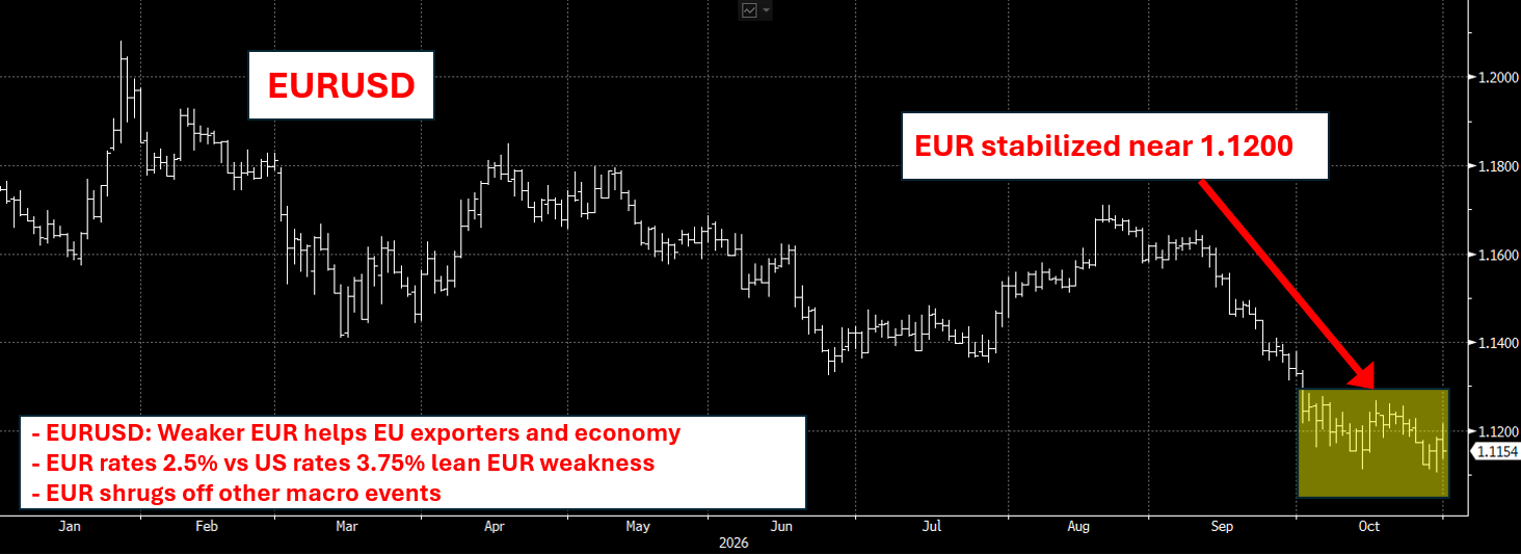
EURUSD 1.1% early in October but stabilized near 1.1200 during the last 2 weeks of the month. The Eurozone beat Q3 GDP estimates at 0.4% QoQ, but France contracted and debt concerns are deepening. Inflation expectations have risen sharply, and forecasters now see 3.0% for 2026. The ECB held at 2.5% in October despite the recent inflation of 3.5%. December is the next live meeting and the market is pricing a third increase when new forecasts land. EUR has shed more than 5% against the dollar this year. Remember, energy exposure is much higher for Europe, and oil prices will have more impact on any meaningful change in the SoH.
USDCAD
Source: Bloomberg Finance LP
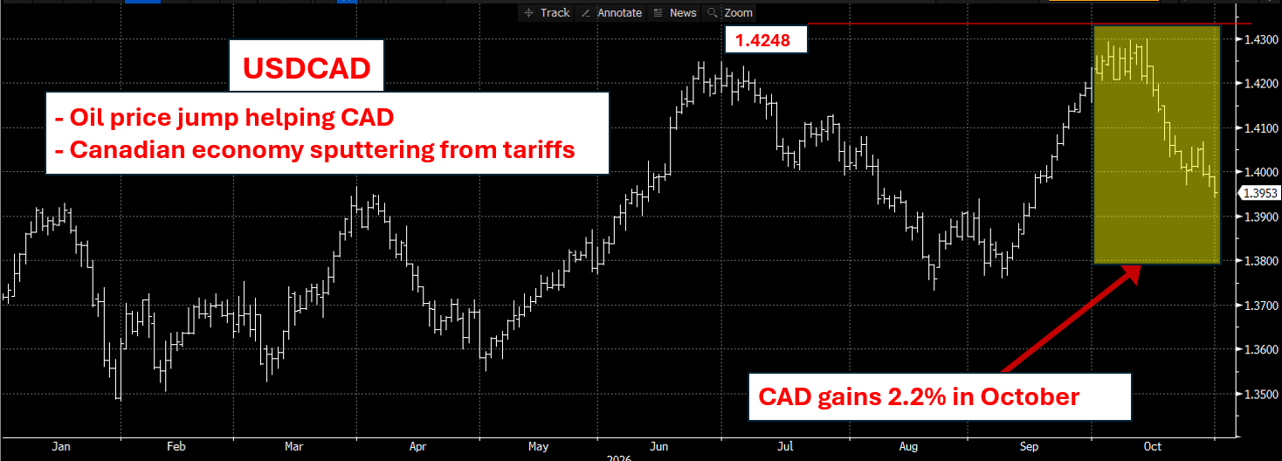
CAD gained 2.2% vs the USD in October, moving higher on oil prices. The Bank of Canada hiked 25bps to 2.50% which was its first hike in in over three years. Still, the economic data in Canada is softening. Q3 GDP is tracking 1.3% annualized with August flat and September preliminarily negative. Employment fell 68,300 in September against a +10k consensus. The loonie touched multi-month lows after the jobs miss in early October. With no BoC meeting in November, the next decision is December. Headline CPI rose to 3.1% on gasoline, so inflation is still an issue. The growth vs.inflation is handcuffing the BoC, but expect them to err on the side of growth.
USDMXN
Source: Bloomberg Finance LP
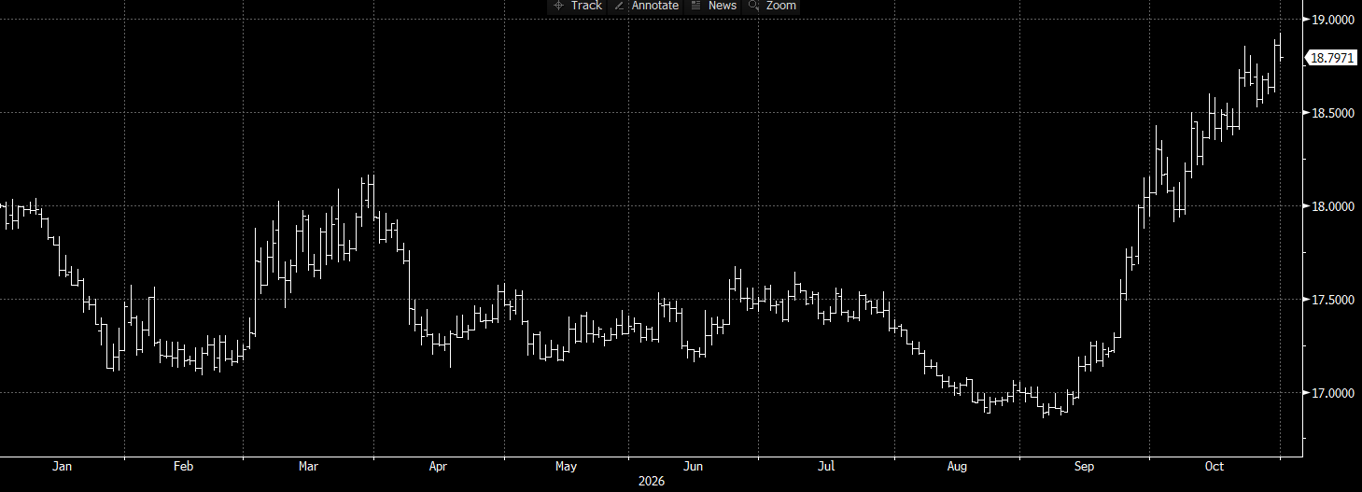
The MXN lost another 2.5% in October and is seeing wild daily swings in price. Mexico's economy accelerated sharply in Q3, with GDP rising 3.2% YoY on investment and export strength. Bi-weekly CPI for early October came in at 3.62%, above estimates, making a near-term cut harder to justify. Banxico meets November 5 and expectations are holding at 6.50%, but there is a chance of hiking rates to combat inflation with this strong economy. Carry dynamics remain supportive as long as the rate differential holds. US-Mexico tariff talks are reportedly continuing, with signals that Section 232 relief may be on the table. All this economic good news, but the MXN is weak? This means volatility with larger daily ranges as this is sorted by markets.
USDCNY
Source: Bloomberg Finance LP
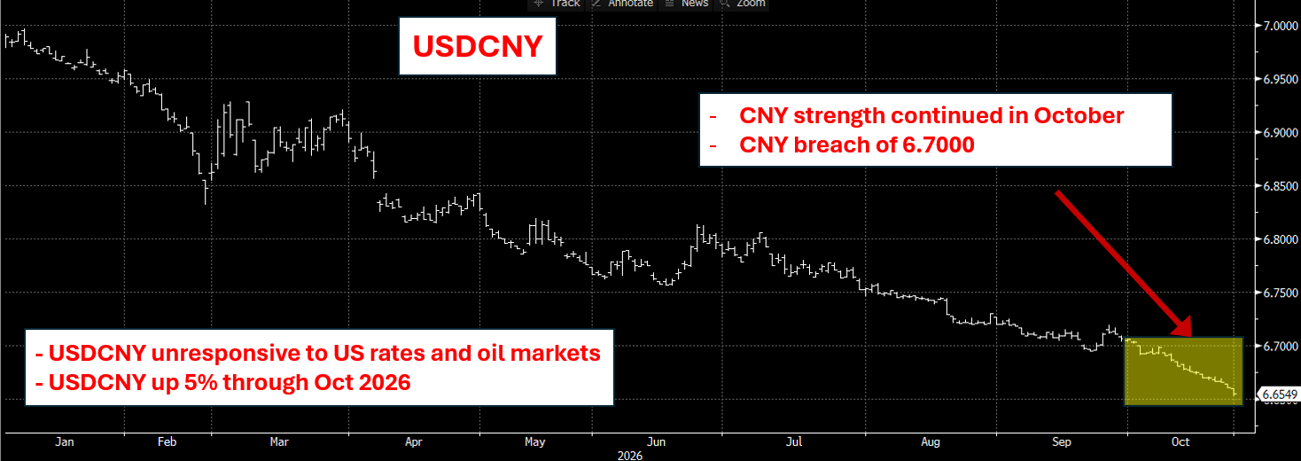
The CNY continued its steady gains in October, gaining 0.9% vs the USD. Its clear the PBOC has a target, but what that target is remains a mystery. The yuan posted its best month since May, with the PBOC fixing stronger for 13 straight sessions and USD/CNY breaking below 6.65 for the first time since June 2022. The central bank revealed its overnight reverse repo rate at 1.25% marking a meaningful step toward an overnight-rate framework. Export growth surged 36% YoY in September, keeping the trade surplus on track for a record year despite US tariffs. China may be thinking “we need more domestic consumption” and a stronger CNY helps to achieve a stronger internal economy.
USDJPY
Source: Bloomberg Finance LP
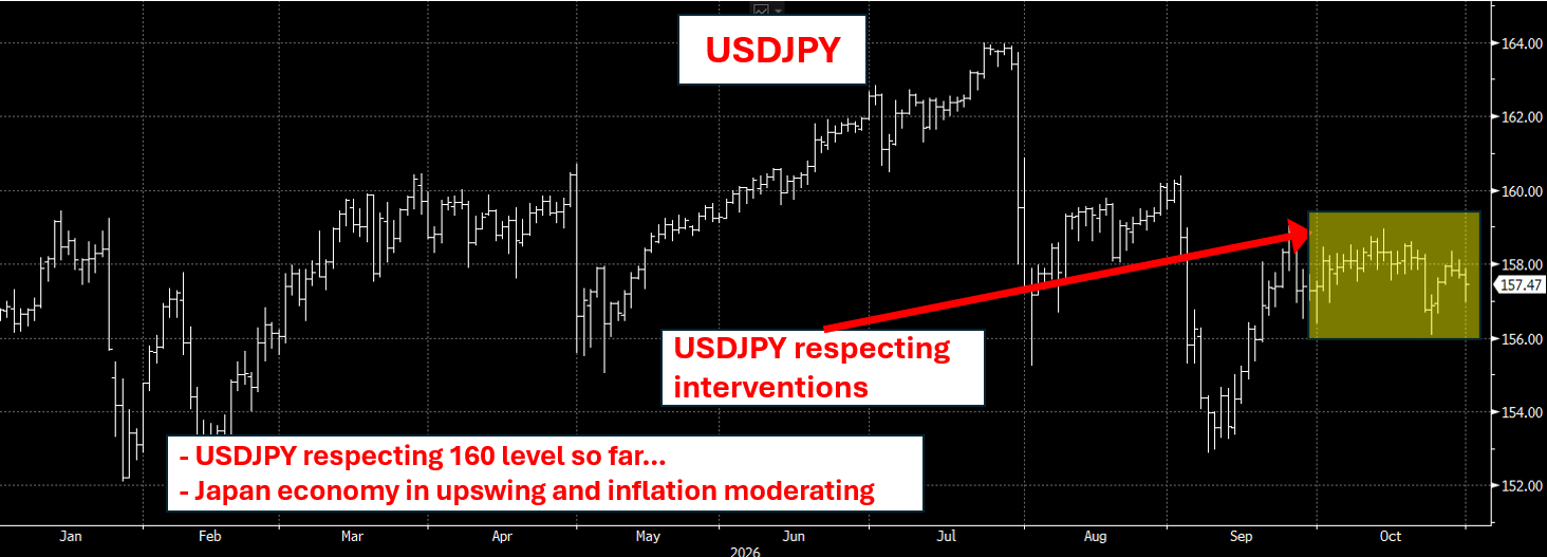
The JPY had a quiet month with constrained trading near the 158 level for most of the month. Tokyo CPI held at 2.6% in October and Ueda confirmed underlying inflation is approaching 2%. Real wages rose for an eighth straight month, unemployment fell to 2.4%, and industrial production beat estimates. Board member Koeda warned against excessive caution, but inflation is moderating. Finance Minister Katayama renewed verbal intervention warnings after yen weakness followed hot US CPI. No BoJ meeting in November—December is live, and the IMF expects one more hike to neutral. Again in November, expect joint interventions above 160.
GBPUSD
Source: Bloomberg Finance LP
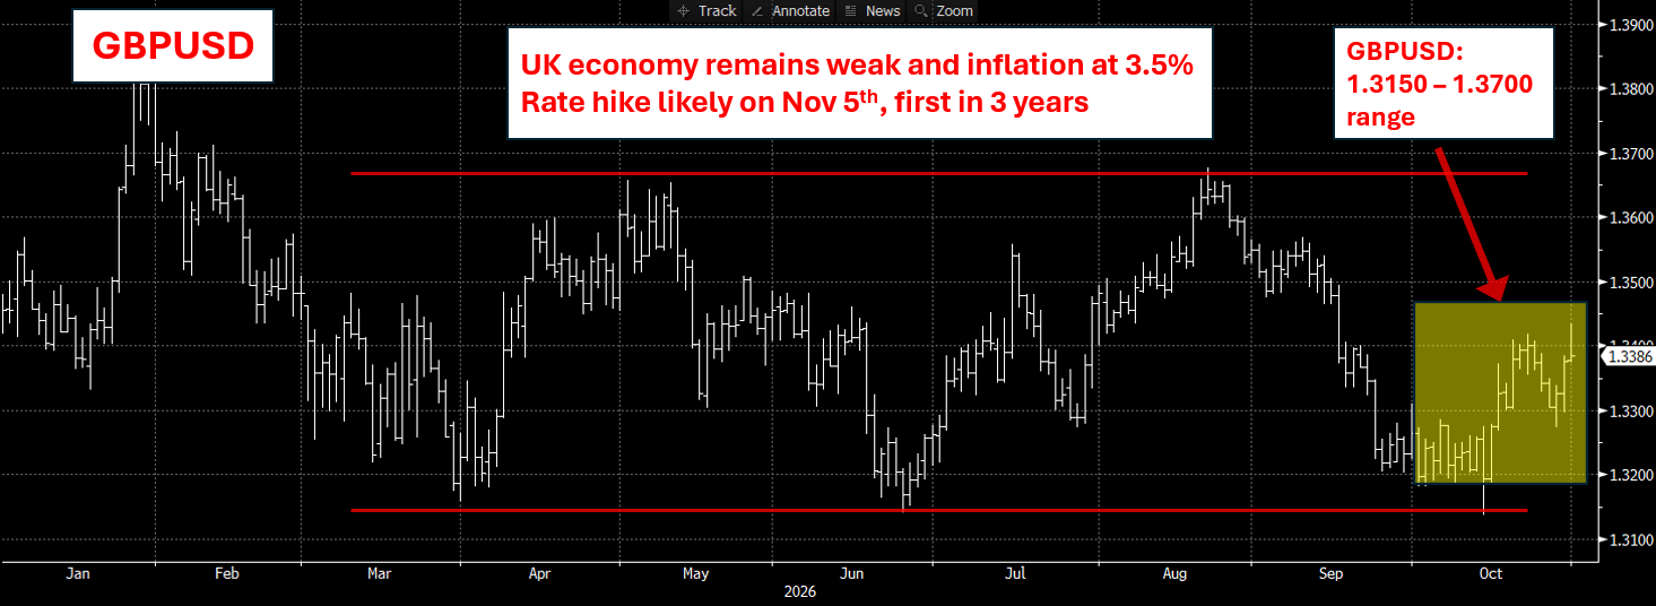
The GBP rebounded vs the USD with a small gain of 1.1% and remained inside its 1.3150 – 1.3700 trading range. UK CPI hit 3.5% in September and the Bank of England is widely expected to hike at its November 5 meeting. This would be the first rate increase in over three years. August GDP surprised to the upside at +0.1% MoM. Wage inflation pass-through from the energy shock remains limited per BoE agents, which may temper the ratpace beyond November. UK debt has crossed £3 trillion for the first time.
Associated Bank can transact foreign exchanges in more than 100 currencies. Companies interested in learning more about making payments in foreign currencies or in hedging currency exposures should contact their Associated Bank Relationship Banker or the bank’s Corporate Foreign Exchange Department at 866-524-8836 or email fxcapmarkets@associatedbank.com.
All rates shown are indications only and subject to change. Foreign exchange contracts are subject to foreign currency exchange risk and are NOT deposits or obligations of, insured or guaranteed by Associated Bank, N.A. or any bank or affiliate, are NOT insured by the FDIC or any agency of the United States, and involve INVESTMENT RISK, including POSSIBLE LOSS OF VALUE. This material is provided to you for informational purposes only; and any use for other than informational purposes is disclaimed. It is a summary and does not purport to set forth all applicable terms or issues. It is not intended as an offer or solicitation for the purchase or sale of any financial product and is not a commitment by Associated Banc-Corp, its subsidiaries or affiliates, as to the availability of any such product at any time. The information herein is not intended to constitute legal, tax, accounting, or investment advice, and you should consult your own advisors as to such matters and the suitability of any transaction. We make no representations as to such matters or any other effects of any transaction. In no event shall we be liable for any use of, for any decision made or action taken in reliance upon, or for any inaccuracies or errors in, or omissions from, the information herein. The views expressed here are solely those of the author and do not reflect the views of Associated Banc-Corp, its subsidiaries or affiliates.
